
Applied Materials (AMAT) Q4 Earnings Preview: Can AI Equipment Demand Support a $10B+ Quarter and Sustained High Growth?
 2026/11/12 02:44
1. Investment Highlights
Applied Materials (AMAT.US) will report FY2026 Q4 results after the U.S. market close on November 12, 2026. Wall Street consensus expects revenue of approximately $10.30 billion (+51.5% YoY; company guidance midpoint $10.25 billion) and non-GAAP EPS of approximately $4.06 (+87.1% YoY; company guidance midpoint $4.02). The company has beaten estimates in each of the past eight quarters. Management previously stated that AI demand is driving record results and projected growth faster than the overall market into 2027. Investors will focus on whether AI-related equipment orders can fully offset traditional cycle pressure and whether next-quarter guidance sustains the high-growth trajectory.
Focus 1: AI-Driven Demand for Advanced Logic, DRAM, and Advanced Packaging
AI compute expansion is the core growth engine. Management expects leading-edge foundry-logic, DRAM (including HBM), and advanced packaging to account for roughly 80% of wafer fab equipment (WFE) growth in 2026–2027. Applied Materials holds leading positions in these areas and is targeting market-share gains. The Q4 revenue guidance midpoint has already crossed the $10 billion mark (+51% YoY), with advanced packaging revenue expected to grow more than 70% in calendar 2026. The market will look for confirmation that order and shipment momentum in these high-value segments remains strong.
Focus 2: Can Margin Expansion Continue After Eight Consecutive Beats?
Unlike some peers, Applied Materials has improved its gross margin year-over-year for 13 consecutive quarters. Non-GAAP gross margin was approximately 50.4% in Q3, and management expects Q4 to remain roughly flat. Pricing power, product mix, and operating leverage are key. Continued expansion or at least stability would reinforce the “high growth + high profitability” narrative; any pressure from capacity ramp costs or input inflation could weigh on earnings leverage.
Focus 3: Declining China Revenue Share and Export Control Impact
China’s revenue contribution has declined from earlier highs to approximately 28%. Export controls and geopolitical factors remain variables. Investors will watch whether mature-node demand in China still provides support and whether growth outside China (especially from U.S. and other advanced-node customers) can fully offset any weakness. Management has previously highlighted extended demand visibility, with some customer discussions reaching as far as 2030.
Focus 4: Sustainability of Next-Quarter and Full-Year Guidance
Q4 is a critical test of whether the current high-growth pace has peaked. Consensus sits slightly above the company’s guidance midpoint, so an in-line result alone may not be enough. The market will closely monitor Q1 FY2027 guidance (some analysts expect sequential growth) and whether management reaffirms or strengthens its view that 2027 growth will outpace the overall market. The services business (AGS), expected to grow more than 20% in 2026, also serves as a stabilizing factor.
3. Risks and Opportunities
Upside Catalysts:
- Revenue and EPS significantly above consensus (especially strong advanced packaging and DRAM-related revenue), with an upward revision to next-quarter guidance.
- Gross margin continues to expand or holds steady at elevated levels, confirming pricing power and mix benefits.
- Management reaffirms or raises the outlook for 2027 growth outpacing the overall market, with further extension of long-term order visibility.
Downside Risks:
- Results only meet or fall slightly short of the guidance midpoint without an upward revision to the outlook, raising questions about growth sustainability.
- Further decline in China demand or worse-than-expected impact from export controls that non-China growth cannot fully offset.
- Margin pressure from capacity ramp costs or supply-chain constraints.
4. Trading Strategy Considerations
Bull Case: If AI-related equipment demand (advanced logic, DRAM, and advanced packaging) clearly exceeds expectations, margins remain stable, and management provides constructive next-quarter or full-year guidance, Applied Materials’ positioning as a core AI wafer-equipment supplier could be reinforced, supporting valuation recovery.
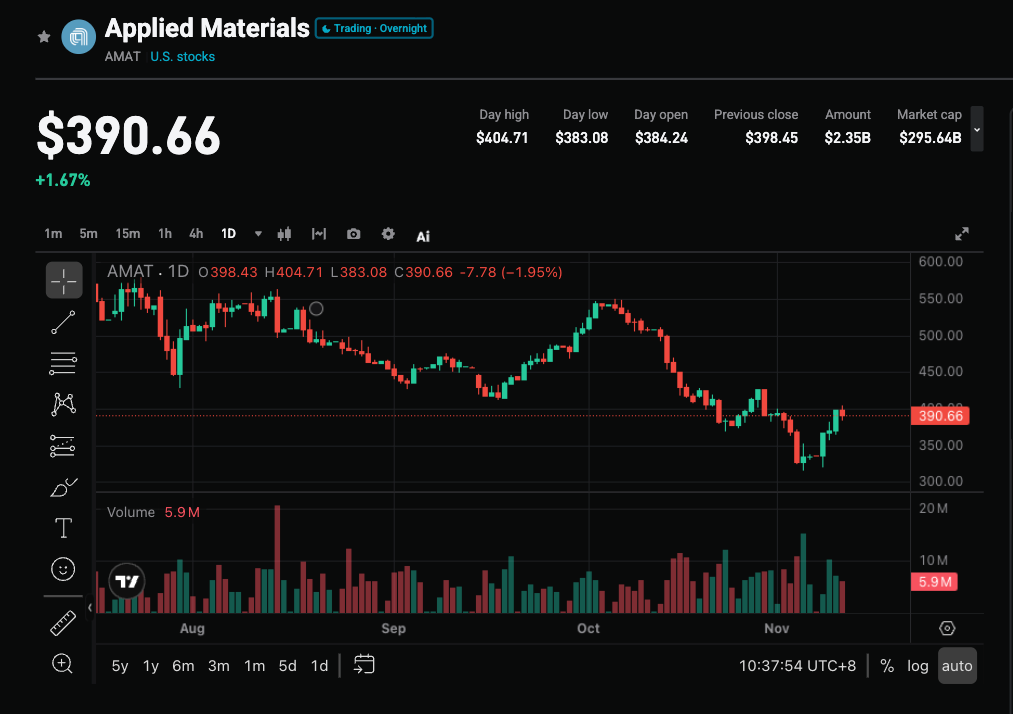
Bear Case: If results merely meet the midpoint, guidance is cautious, or margins decline, further profit-taking could occur—especially after the recent pullback (roughly -14.5% over the past month).
Key Metrics to Watch:
- Total revenue and YoY/QoQ growth
- Advanced packaging, DRAM, and advanced logic-related revenue
- Non-GAAP gross margin and operating margin
- Whether Q1 FY2027 and full-year guidance is raised
- China revenue share and contribution from non-China growth
Operational Notes: A clear beat with constructive guidance may present opportunities on pullbacks; softer results or cautious outlook warrant caution on near-term volatility. Position sizing and stop-loss levels should be adjusted according to individual risk tolerance.
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
After the Brazilian election, political discount deepens; Morgan Stanley remains bullish on Petrobras (PBR.US), focusing on fuel pricing and dividends
Morgan Stanley still maintains its most optimistic "Overweight" rating, but has lowered its year-end 2027 target price from $31 to $25.

Corning (GLW.US) receives initial "Buy" rating from Jefferies! AI factories driving a fiber optic rush, with a potential global supply gap of up to 30%
For Corning, the recent profit growth mainly comes from the expansion of AI clusters. As the number of optical links crossing cabinets and campuses increases, customers need to deploy more optical fibers within limited conduit and cabinet space, thus driving demand for high-density optical cables and connection systems.

Synergies Will Take Longer! Citi Raises Skydance (SKYD.US) Synergy Costs to $4 Billion but Maintains "Buy" Rating
Citibank has released a Q3 2026 model update report for Skydance Corp, maintaining its "Buy" rating and a target price of $10.
Crypto prices
More


