
Palantir Q3 Earnings Preview: Can U.S. Commercial High Growth Continue and Will Full-Year Guidance Be Raised?
 2026/11/02 02:17
🔥 US Stock Hotspot Radar is Live! Content: 3 major themes + 6 selected stocks + 7 key events. Where are this week’s opportunities? Click the link to see all 22 trading directions in one chart →
1. Investment Highlights Overview
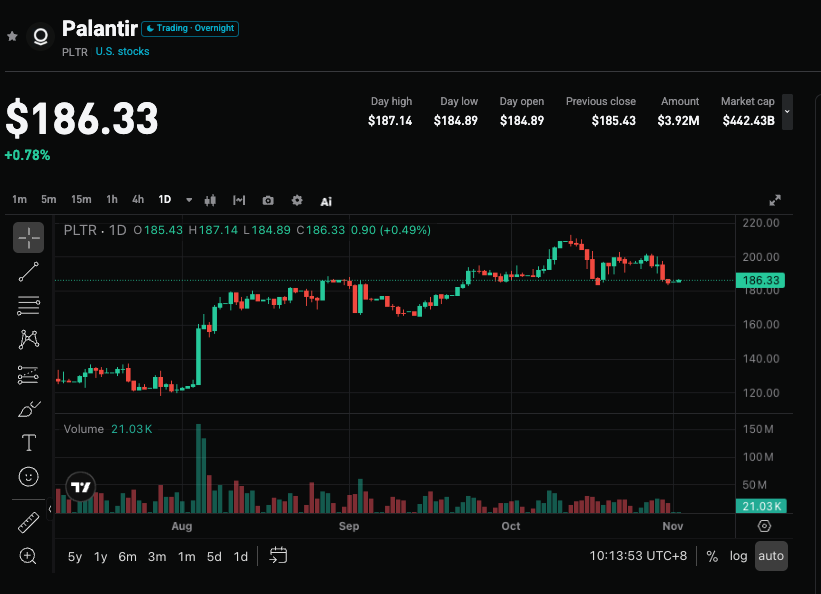
Palantir (PLTR.US) will report its fiscal 2026 third-quarter results after the U.S. market close on November 2, 2026, with the conference call scheduled for 5:00 p.m. ET. Wall Street consensus expects total revenue of approximately $2.18 billion (about +84.7% YoY) and adjusted EPS of $0.41 (nearly double year-over-year). The company’s own Q3 guidance is for revenue of $2.160–$2.164 billion (midpoint around +83% YoY) and adjusted operating income of $1.292–$1.296 billion. Morgan Stanley, based on channel and partner checks, expects actual revenue to reach $2.27–$2.29 billion (+92–94% YoY), marking the 13th consecutive quarter of accelerating growth. However, the firm maintains an Equal-weight (neutral) rating, noting that the high valuation has already fully priced in optimistic expectations and that a pullback would offer a better entry point. The market is focused on whether U.S. commercial growth can remain elevated, the room for a full-year guidance raise, and how the stock digests its elevated valuation.
Focus 1: Can U.S. Commercial High Growth Continue
U.S. commercial remains the core growth engine. In Q2 this segment surged 149% YoY to $764 million, but tougher comparisons and a slowdown in customer growth (from 42% to 35% YoY, ending at 653 customers) make further acceleration more difficult. Both the market and institutions (including Morgan Stanley and Citi) view sustaining roughly 140% growth as a positive outcome. Investors will closely watch net retention, large-deal momentum, and actual monetization progress of the AIP platform to assess sustainability.
Focus 2: Magnitude of the Beat and Government Business Resilience
Company guidance implies roughly +83% growth, while consensus sits around +85% and Morgan Stanley sees +92–94% (a 5–6% beat, smaller than Q2’s 7.6%). U.S. government revenue grew 90% YoY to $809 million in Q2 and is expected to remain a steady contributor. A result meaningfully above the company’s guidance upper end and approaching or exceeding $2.27 billion would confirm strong AI-driven demand; merely hitting the midpoint of guidance could disappoint.
Focus 3: Room to Raise Full-Year Guidance and Q4 Outlook
Current full-year revenue guidance stands at $8.150–$8.158 billion (about +82%). Q4 guidance will be the most important indicator and will determine whether the full-year outlook is raised again. Some institutions (such as Citi) expect another roughly 10-percentage-point increase in the full-year growth guide, driven primarily by the U.S. business. An upward revision accompanied by constructive commentary would support the valuation; a cautious outlook could pressure the stock.
Focus 4: Profitability, Expense Control, and High-Valuation Digestion
The company has flagged rising operating expenses in Q3 (seasonal hiring and product/marketing investment), and adjusted gross margin may face pressure from cloud hosting costs. Attention will center on whether adjusted operating margin can stay near the 60% level and on free-cash-flow performance. The stock has risen substantially since the last report; the elevated valuation (Morgan Stanley DCF optimistic scenario of $295 carries only ~9.3% implied probability, while the pessimistic case falls to $81) means even solid results could produce a mixed reaction, with a pullback viewed as a better entry.
3. Risks and Opportunities
Upside Catalysts:
- U.S. commercial growth significantly above 140%, or total revenue reaching $2.27 billion or higher, confirming sustained high growth.
- A clear beat plus an upward revision to full-year revenue guidance, with profitability remaining stable.
- Government and international commercial results exceeding expectations, with positive customer feedback on the AIP platform.
Downside Risks:
- U.S. commercial growth slowing below 140%, or total revenue merely meeting the company’s guidance midpoint without a meaningful beat.
- Failure to raise full-year guidance or a cautious Q4 outlook, compounded by expense pressure on margins.
- In a high-valuation environment, even good numbers could trigger “sell-the-news” profit-taking.
4. Trading Strategy Suggestions
Bull Case: If U.S. commercial and total revenue meaningfully exceed consensus (approaching or surpassing $2.27 billion) and management raises full-year guidance while offering constructive commentary, confidence in Palantir as a leading AI software platform could strengthen and support a valuation recovery.
Bear Case: If results merely meet or only modestly exceed company guidance, commercial growth slows, or guidance remains cautious, profit-taking could emerge, especially amid elevated valuation and broader tech volatility.
Key Metrics to Watch:
- Total revenue and year-over-year growth (whether above $2.27 billion)
- U.S. commercial revenue growth and contract trends
- Whether Q4 and full-year revenue guidance are raised
- Adjusted operating margin and free-cash-flow performance
Actionable Notes: On a large beat with positive guidance, look for pullback opportunities to build positions. If results are in-line or guidance is soft, watch for near-term volatility and avoid chasing. Position sizing and stops should be adjusted according to individual risk tolerance.
Disclaimer: The above content is for reference only and does not constitute investment advice.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
ECB Picks Digital Euro Network Providers as Pilot Infrastructure Takes Shape

US Stock IPO Analysis | AOJE.US Growth Blueprint Spanning Both Consumer and Industrial Sectors, Driven by Three Key Logic Factors
As both revenue and profit decline, what kind of growth narrative will Aojie Co., Ltd. use to convince Nasdaq investors to buy in?

Crypto prices
More


